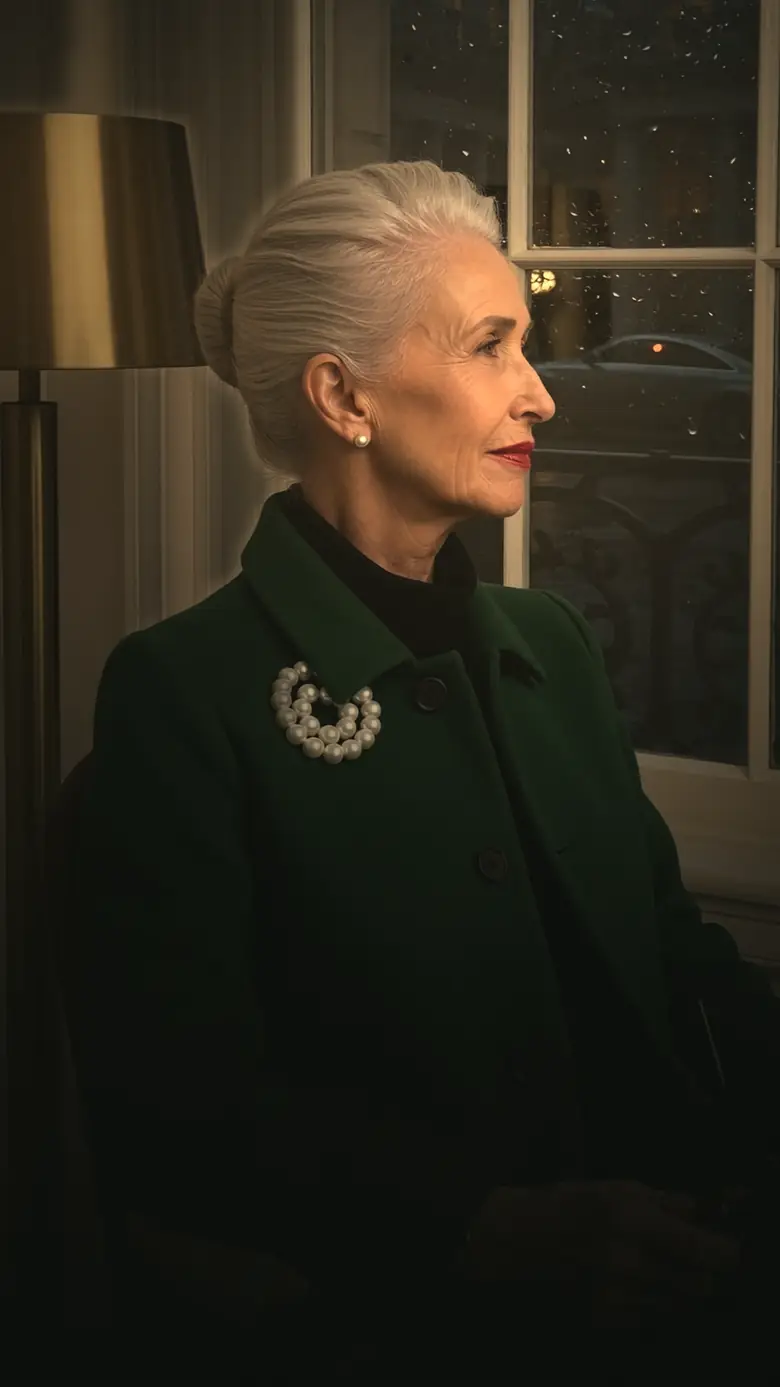
Maureen Pike, silver-haired, in a money-green coat with a pearl brooch, seated in profile beside a brass lamp and a rain-spotted window at night.

Seven o'clock · The Door

A guide to retirement accounts

The Standing Order

Which account gets your next dollar, in what order, and how to set it all running on its own. Seven evenings.

Maureen is an AI character. No subscription.

Rain on a tall window at night, the lit windows of the street opposite blurred in the glass.

Ten past sevenAn observation

Perfectly good accounts. No seating plan.

There is a 401(k) you joined on your first morning and haven't opened since. An IRA opened in a fit of resolve and left sitting in cash. A savings account with a hopeful name. Perhaps an old plan at an old job, waiting quietly to be remembered.

So every payday the money sits wherever it happens to fall, and every so often you lie awake wondering whether it fell in the wrong place.

Every member arrives with a muddle. Nobody is asked about it at the door.

Half past sevenThe Seating Plan

House Rule V · The Order of Precedence

Every new dollar takes the highest empty chair.

At a proper dinner nobody argues about where to sit. The order was settled long before anyone arrived, the cards are on the table, and everyone is fed. Your money deserves the same arrangement. Here is a commonly taught order. Scroll, and I'll seat you.

  1. The Floor Before anyone sits downBefore anyone sits down

    Before anyone sits down

    A cash cushion in an ordinary savings account, for the boiler, the car and the month between jobs. Retirement accounts are not for emergencies. Raiding one is one of the most expensive ways ever devised to mend a boiler.

    A cash cushion in an ordinary savings account, for the boiler, the car and the month between jobs. A retirement account is not an emergency fund.

    In the UKBefore anyone sits down

    A cash cushion in an ordinary savings account, for the boiler, the car and the month between jobs. A pension is not for emergencies, and neither is an ISA you've promised to your future self.

    A cash cushion in an ordinary savings account, for the boiler, the car and the month between jobs. Not a pension, and not an ISA you've promised your future self.

  2. Chair One The matchYour workplace pension

    The match

    If your employer matches what you put into your 401(k), put in at least enough to collect every cent of it. Declining a match is turning down a pay rise because the form looked dull.

    If your employer matches your 401(k), put in at least enough to collect every cent. Declining a match is turning down a pay rise because the form looked dull.

    In the UKYour workplace pension

    If you're eligible for auto-enrolment, your employer must pay in, and many will pay more if you do. Collect every penny on offer. If they offer salary sacrifice, ask how it works.

    If you're eligible for auto-enrolment, your employer must pay in, and many pay more if you do. Collect every penny on offer. Ask how salary sacrifice works.

  3. The Checkpoint Expensive debtExpensive debt

    Expensive debt

    Here the schools genuinely part company. One says clear expensive debt before another dollar is invested. The other says keep a small investing habit running while you pay it down. Both are respectable. The book makes you choose one and write it down. The NFCC's nonprofit counsellors help for free if the debts have teeth.

    Here the schools differ: clear expensive debt first, or keep a small investing habit going as you pay it down. Both are respectable. Choose one and write it down.

    In the UKExpensive debt

    Here the schools genuinely part company. One says clear expensive debt before another pound is invested. The other says keep a small investing habit running while you pay it down. Both are respectable. StepChange and Citizens Advice help for free if the debts have teeth.

    Here the schools differ: clear expensive debt first, or keep a small investing habit going as you pay it down. Both are respectable. StepChange and Citizens Advice help, free.

  4. Chair Two An IRA, usually a RothA Lifetime ISA, if you're 18 to 39

    An IRA, usually a Roth

    An account you open yourself, outside work, usually with a far longer menu than a workplace plan. Roth or traditional turns on whether your tax rate is higher now or later, and nobody can tell you that for certain. Check this year's income limits on IRS.gov.

    An account you open yourself, outside work, with a longer menu than most workplace plans. Roth or traditional turns on whether your tax rate is higher now or later. Limits: IRS.gov.

    In the UKA Lifetime ISA, if you're 18 to 39

    For a first home or for later life. The government adds a bonus, and there is a charge for taking the money out for anything else. If you pay higher-rate tax or your employer offers salary sacrifice, more into the pension often wins instead; MoneyHelper sets out both. Check the rules on GOV.UK before you start.

    For a first home or later life. The government adds a bonus; other withdrawals carry a charge. Higher-rate taxpayers may do better with more pension: MoneyHelper sets out both. Check GOV.UK.

  5. Chair Three Back to the 401(k)A stocks and shares ISA

    Back to the 401(k)

    Raise your contribution towards the yearly maximum. You may not reach it this year. Most people don't, at first. What matters is the direction.

    Raise your contribution towards the yearly maximum. You may not reach it this year. Most people don't, at first. What matters is the direction.

    In the UKA stocks and shares ISA

    Growth and withdrawals free of UK tax, and you can take the money out when you like. The flexible one. Check this year's allowance on GOV.UK.

    Growth and withdrawals free of UK tax, and you can take the money out when you like. The flexible one. Check this year's allowance on GOV.UK.

  6. Chair Four The HSA, if you're eligibleMore into the pension, or a SIPP

    The HSA, if you're eligible

    Only with a qualifying high-deductible health plan, so check before you get excited. Some teachers seat it straight after the match. Your call. Write it down.

    Only with a qualifying high-deductible health plan, so check before you get excited. Some teachers seat it straight after the match. Your call. Write it down.

    In the UKMore into the pension, or a SIPP

    Tax relief on the way in, like your workplace pension, and with a SIPP you choose the investments yourself. It is for later life: you can't touch it until the minimum pension age, which GOV.UK lists.

    Tax relief on the way in, like your workplace pension. A SIPP lets you choose the investments yourself. It is for later life: GOV.UK lists the minimum pension age.

  7. Chair Five The taxable accountAn ordinary investment account

    The taxable account

    No tax shelter at all and no yearly maximum, which is exactly why it sits last. Many people never reach this chair, and that is not failure.

    No tax shelter at all and no yearly maximum, which is exactly why it sits last. Many people never reach this chair, and that is not failure.

    In the UKAn ordinary investment account

    No tax shelter at all and no allowance, which is exactly why it sits last. Many people never reach this chair, and that is not failure.

    No tax shelter at all and no allowance, which is exactly why it sits last. Many people never reach this chair, and that is not failure.

A commonly taught order. Limits: IRS.gov, GOV.UK.A commonly taught order, not the only one. Where sensible people differ, the book shows both sides and you choose. Limits change every year: IRS.gov in the US, GOV.UK in the UK.

Skip ahead

A commonly taught order, not the only one. Where sensible people differ, the book shows both sides and you choose. Limits change every year: IRS.gov in the US, GOV.UK in the UK.

Knowing the order takes a minute. Setting it running takes seven evenings. That is the book.

Buy The Standing Order · $27

A quarter past eightThe Programme

Seven evenings. One finished thing each night.

Each evening takes about an hour, always in the same order: I talk, you act, you write down what you decided, and you sign the book. One a week, or seven in a row. A standing order is what we call a payment that goes out on its own, every month, without asking you. That is the whole idea.

The Standing Order

Programme for seven evenings

  1. Evening One

    The Written Life

    Decide what the money is for before you decide where it goes.

    I If it isn't written down, it's a mood, not a plan.

    You leave with The life worth paying for, in ink.

  2. Evening Two

    The Four Courses

    Four courses, and none of them is called “sorry”.

    II Before payday, each dollar is told which course it goes to: Fixed, Future, Plans, Pleasure. The Pleasure course is not optional.

    III Move the big chairs, not the teaspoons. Your coffee was never the problem.

    You leave with A monthly plan, and the big costs worth moving.

  3. Evening Three

    The Stood Drink

    Your employer has offered to buy you a drink. Let them.

    IV When your employer offers to match, you never refuse.

    You leave with Your match and contribution in ink, changed tonight if short.

  4. Evening Four

    The Order of Precedence

    Which account gets your next dollar, settled once, so you stop asking.

    V Every new dollar takes the highest empty chair.

    You leave with Your own Seating Plan.

  5. A Word in the Cloakroom: a short letter at the halfway mark, placed exactly where a book like this usually gets put down.

  6. Evening Five

    The Bill of Fare

    Read what the fund charges before you read what it promises. Then choose something dull.

    VI Read what the fund charges before you read what it promises.

    VII One broad, cheap fund you understand beats ten clever ones you don't.

    You leave with Every fund you hold and its cost, and a one-line policy.

  7. Evening Six

    The Empty Glass

    An account is not an investment. It is a glass. Something has to be poured into it.

    VIII Money in an account is not invested until you have chosen what it buys.

    You leave with An IRA opened, its transfer set, the money poured in.

  8. Evening Seven

    Payday Does the Work

    If it needs remembering, it isn't automated yet.

    IX If it needs remembering, it isn't automated.

    X Every pay rise, your contribution climbs a point before you have time to miss it.

    You leave with Every automatic transfer drawn, and next year's rise booked.

  9. Afterwards

    The Annual Meeting

    One hour a year, same agenda, for the rest of your life.

    XI Miss an evening, come to the next one. No catching up, no starting again.

    XII One hour, once a year, same agenda.
Ten to nineThe House Rules

Twelve rules. One page.

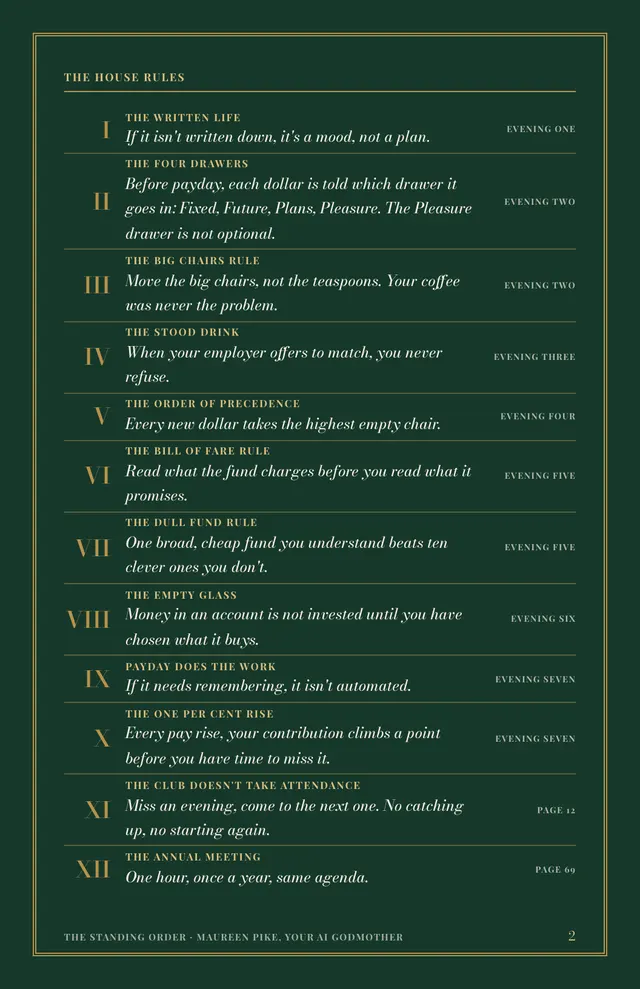
Page two of the book holds all twelve. Screenshot this if you like; that is what it is for. The book explains each rule and gives you an evening to act on it.

All twelve are on page two of the book. It's the first page below.

  1. The Written LifeIf it isn't written down, it's a mood, not a plan.
  2. The Four CoursesBefore payday, each dollar is told which course it goes to: Fixed, Future, Plans, Pleasure. The Pleasure course is not optional.
  3. The Big Chairs RuleMove the big chairs, not the teaspoons. Your coffee was never the problem.
  4. The Stood DrinkWhen your employer offers to match, you never refuse.
  5. The Order of PrecedenceEvery new dollar takes the highest empty chair.
  6. The Bill of Fare RuleRead what the fund charges before you read what it promises.
  7. The Dull Fund RuleOne broad, cheap fund you understand beats ten clever ones you don't.
  8. The Empty GlassMoney in an account is not invested until you have chosen what it buys.
  9. Payday Does the WorkIf it needs remembering, it isn't automated.
  10. The One Per Cent RiseEvery pay rise, your contribution climbs a point before you have time to miss it.
  11. The Club Doesn't Take AttendanceMiss an evening, come to the next one. No catching up, no starting again.
  12. The Annual MeetingOne hour, once a year, same agenda.
Cover of The Standing Order: Maureen Pike in profile beside a brass lamp and a night window, with the title and the line: Seven evenings. The right accounts, in the right order, running on their own.

Twenty past nineWhat you get

Eighty-three pages, written to be done.

Seven evenings, each with a talk, a short list of things to do tonight with the minutes beside them, a worksheet, and a line to sign. Read it on a screen in the evening edition, or print the edition made for paper and keep it on the desk.

  1. Page 2 of The Standing Order: the twelve House Rules.
    The House Rules: all twelve, on the page you'll keep.
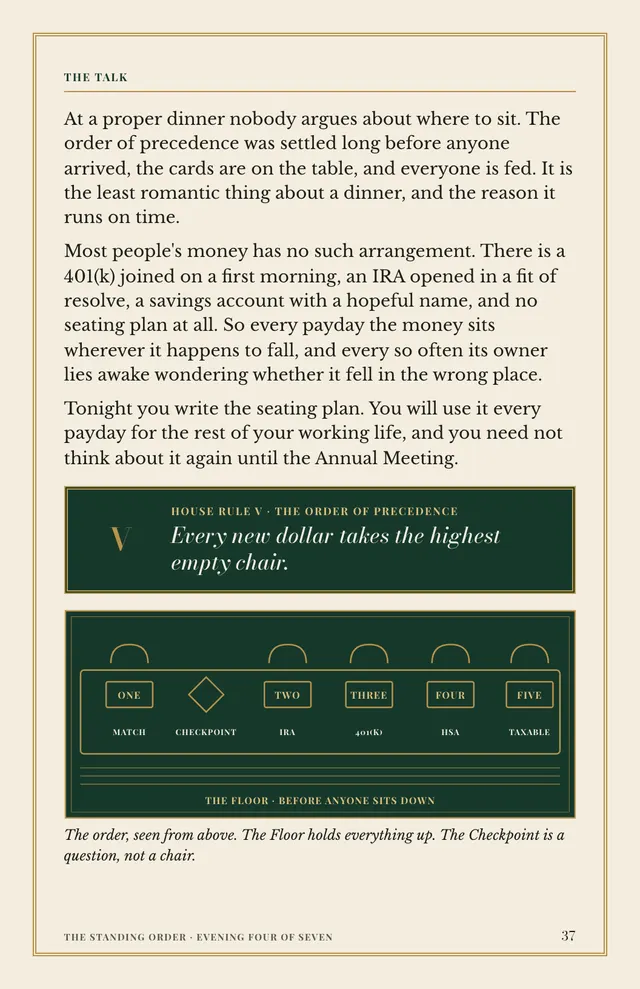
  2. Page 37: Evening Four, The Order of Precedence, opening talk with House Rule V and the Seating Plan diagram.
    Evening Four begins: the dinner, House Rule V, and the Seating Plan, drawn.
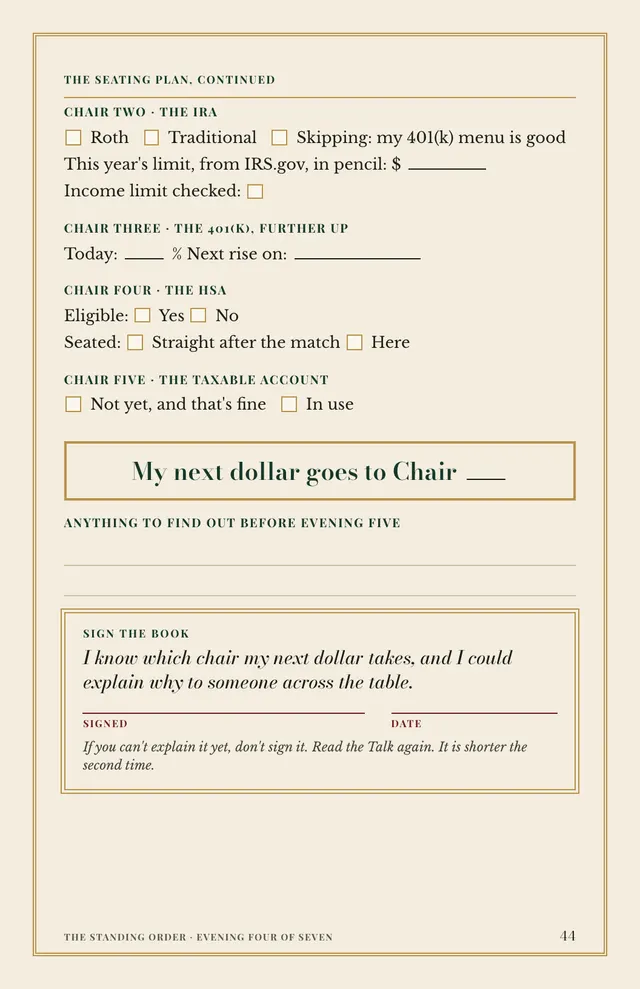
  3. Page 44: the Seating Plan worksheet, Chairs Two to Five, and the Sign the Book panel.
    The worksheet. You fill it in, then you sign the book, but only if you could explain it.
Nine worksheets
One for each evening, plus the Membership Card and its re-score. Where you write what you decided, in ink.
The UK boxes
On every evening: workplace pension, ISA, Lifetime ISA and SIPP.
The Cellar Book
Every fund you hold, what it holds and what it costs, with fourteen fund-page terms explained on the page beside it.
Members' arrangements
Pages for late starters, the self-employed, irregular income, couples, and debt with teeth.
Five bonuses
The Short Order, the five moves that matter most, in one evening. Questions for the Benefits Desk, ready to ask. The Lost Property Office, for finding old workplace accounts. The Annual Meeting Agenda, one printable page. The Translation Card, US accounts and their nearest UK cousins.

PDF · 83 pages · 5.5 × 8.5 in, close to A5 · Priced in US dollars

Buy the guide · $27

Maureen Pike's hands holding folded tortoiseshell sunglasses, in a money-green coat with a pearl brooch, by a window at night.

Ten to tenA word from Maureen

People see the pearls and assume the answer must be clever.

It never is. It is dull, it is in the right order, and it happens without you. That is the whole trick, and I would rather sell you the dull truth than an exciting guess.

I am an AI character, and I've never told you what I own or earn. I shan't start now, because none of it would prove a thing about your money. What I can do is explain, slowly and in order, so that you never sign anything you don't understand.

It's for you if

You're salaried, you have a 401(k) or a workplace pension you joined on your first morning and haven't opened since, and you would rather set it up properly once than worry about it every month. Starting late? There are pages for you too. Late is not never.

Twenty past tenThe bar

Asked at the bar.

What's in the book?

Two PDFs, Evening for screens and Print for paper, the same eighty-three pages in each: seven evenings, nine worksheets, twelve House Rules and five bonuses.

I'm in the UK. Is it any use to me?

Yes. The book is written US-first, and every evening has an “If you're in the UK” box covering the workplace pension, ISA, Lifetime ISA and SIPP. There is a Translation Card at the back. The manners are the same; the furniture is different.

Will it tell me what's right for me?

No. I am an AI character and this is education, not advice. For advice on your own situation, look for a fee-only fiduciary in the US. In the UK, start with MoneyHelper, which is free and impartial.

Will it tell me what to buy?

No. It names no funds and no firms. It teaches you to read a fund's cost and what it holds, so you can choose something broad, cheap and dull yourself.

Will it promise me a return?

No. Nobody can. Investments can fall as well as rise, and you may get back less than you put in.

Does it print this year's limits?

No. They change every year, so the book sends you to IRS.gov or GOV.UK every time. It doesn't give you a retirement number either; that is a different book.

I've only got one evening.

Then start with The Short Order, the first bonus: the five moves that matter most, in one sitting. Come back for the seven evenings when you can.

How do I pay?

Checkout opens soon. The till isn't open yet. Nobody is charged at the door. When it opens, I'll say so on my channels.

Is there really a club?

No. There is no club, and I'm an AI character. It says so on the cover of the book, inside it, and at the foot of this page. The principles are real and widely taught. My own money is part of the fiction, which is exactly why I never offer it as proof.

Twenty to elevenSign the book

In my club, you sign only what you could explain.

I've spent my life telling people not to sign what nobody will explain. So every evening ends with one sentence and a line for your signature. You sign it only if you could explain what you've just done to someone across the table. If you can't yet, read the talk again. It is shorter the second time.

Sign the book · Evening Four

I know which chair my next dollar takes, and I could explain why to someone across the table.

SignedDate

House rule: if they won't explain it, don't sign it.

An open members' book with blank cream pages and a fountain pen, lit by a brass lamp at night.

Sign the book · Evening Four

I know which chair my next dollar takes, and I could explain why to someone across the table.

SignedDate

House rule: if they won't explain it, don't sign it.

A long club table laid for one at night, five candles lit down its centre.

Eleven o'clockAnd then

One hour a year, for the rest of your life.

After the seventh evening, nothing happens. You'll feel oddly bereft. That quiet is the sound of it working.

Cover of The Standing Order: Maureen Pike in profile beside a brass lamp and a night window, with the title and the line: Seven evenings. The right accounts, in the right order, running on their own.

The Standing Order

Maureen Pike's members' guide to retirement accounts

$27

One subscription: none. Two editions. Membership for life.

Buy the guide · $27

Cover of The Standing Order.

The till

Checkout opens soon.

The Standing Order is written and waiting at the desk. The till isn't open yet, and I won't take your money through one that isn't ready.

There is no form here and nothing to fill in. When the till opens, I'll say so on my channels.

The Standing Order · PDF, two editions · $27, once

If they won't explain it, don't sign it.

Back to the club